No Spend Month Rules: The 2026 Playbook That Gets You Past Day 10 (Written-Rules Method)

Here’s an honest confession to start with: a no-spend month is not easy, and anyone who tells you otherwise is selling something. I’ve attempted it twice myself. The first attempt died on day nine — a random Tuesday evening, tired, boring fridge, phone one thumb-swipe from a food delivery app. The second attempt made it to day thirty, and the difference had nothing to do with willpower.
The second time, I did exactly one thing differently before day one: I wrote my rules down on paper and stuck them on the fridge. Same person, same temptations, completely different outcome. That’s what this guide is about: an actual playbook of no spend month rules that survives real life — takeout cravings, birthday dinners, and the force that makes you browse stores at 11 PM.
Quick answer: A no-spend month is a 30-day challenge where you spend only on true essentials — rent, utilities, basic groceries, transport, medical needs — and pause every discretionary purchase. The rules work when you write them down before day one, decide every gray area in advance, and give your saved money a specific destination.
What a No-Spend Month Actually Is (and Isn’t)
A no-spend month is a deliberate 30-day freeze on discretionary spending. You keep paying for everything that keeps your life running — housing, bills, groceries, transport to work, medicine, minimum debt payments — and you stop spending on everything else. No restaurants, no new clothes, no coffee runs, no doom-scrolling through online sales.
What it isn’t: a punishment or a moral judgment on spending. It’s a reset button — one month of paying attention so you can see, with your own eyes, where your money has been leaking. And it’s having a moment: throughout 2026, finance writers and news outlets have documented the no-spend and no-buy challenge trend, including the gentler “no-spend weekend” version families use as training wheels. The timing makes sense — prices are up, one-tap payments made spending frictionless, and plenty of people are quietly wondering where their paycheck goes.
The Written-Rules Method: Why Most People Quit by Day 10
Ask around and you’ll hear the same story: “I did great for a week, then I caved.” They didn’t cave because they were weak. They caved because their rules lived in their head — and a rule that lives in your head is just a suggestion your tired brain can renegotiate at 9 PM.
The fix is almost embarrassingly simple: write your no-spend month rules down before day one — on paper, in your phone notes, taped to the fridge — somewhere you’ll actually see them. When the rules are written, the decision is already made. Three lines are enough to start: your start and end dates; your destination (where does the money you don’t spend go — a savings account, a debt payment, a named goal?); and your exception policy for genuine emergencies, decided now while you’re calm.
The Core No-Spend Month Rules
Every successful no-spend month follows the same basic structure. Copy this, then customize it — your rules should fit your actual life.
Always allowed (essentials): rent or mortgage, utilities, insurance, phone bill; groceries (the cooking-at-home kind, with a set weekly budget); transport to work — gas, bus pass, essential car maintenance; medications and doctor visits; minimum debt payments (never skip these); pet food and basic pet care; childcare and school supplies you genuinely ran out of.
Not allowed (discretionary): eating out — restaurants, coffee shops, delivery apps; clothing and accessories (even the “huge sale” ones); home decor, books, gadgets, hobby supplies; beauty treatments and haircuts (unless for a job interview — use judgment); new subscriptions and free trials; gifts bought during the month; alcohol beyond what you own; “treating yourself.”
The golden rule underneath it all: spend on needs, not wants. Obvious — until you have to apply it at 9 PM on a Friday. That’s why the next section exists.
7 Gray-Area Decisions to Make Before Day One
This is where no-spend months are actually won or lost. The black-and-white rules are easy; the gray areas are where you negotiate with yourself at your weakest. Decide all of these now:
1. Groceries vs. eating out. A common rule: if you cooked it from raw ingredients, it’s groceries. The deli rotisserie chicken? Eating out. Decide now.
2. The broken replacement. Your phone charger dies in week two. Rule: replace broken essentials only, cheapest reasonable option, no upgrading.
3. Existing subscriptions. Most people keep them but start zero new ones. Decide whether you’ll pause anything pausable.
4. Gifts and birthdays. Options: a heartfelt card and a rain check, a pre-set small budget, or borrowing from next month’s fun money. Pick one now, not at the party.
5. Kids’ needs. Kid essentials are always allowed; kid wants follow the same freeze as yours. Writing a simple family agreement together turns a private experiment into a team project.
6. Work costs. Dry cleaning for an interview, a haircut before a big presentation — allow genuine career necessities, defined narrowly.
7. The one planned treat. Some of the most sustainable no-spend months include one small planned treat per person per week. It prevents the deprivation spiral that ends the whole challenge. Decide the amount now.
The Failure Protocol: What to Do When You Slip
You might slip — most people do at least once. The protocol that separates a slip from a collapse: don’t quit. One unplanned purchase doesn’t erase twenty good days; the all-or-nothing mindset turns a $12 slip into a “month’s ruined anyway” spree. Log it like data — what you bought, what triggered it, what you’d do differently. Then use the 24-hour rule going forward: any non-essential purchase waits a day. Nine times out of ten, the urge evaporates.
How to Say No Without Ruining Your Social Life
Nobody warns you about this part: the money is manageable; the people are hard. Telling people upfront is ten times easier than excuses in the moment. Scripts that work: “I’m doing a no-spend month — potluck at mine instead? I’ll cook.” “Sitting this one out, but send pictures — next month I’m in.” “I’m on a spending freeze, so your gift is coming in November — and it’ll be good.” Almost nobody judges you for it, and a surprising number will admit they’ve been thinking about the same thing.
Give the Money a Name
The step almost everyone skips: before day one, name a destination for the money you don’t spend — a separate savings account, a specific debt, a named goal like “Christmas fund.” Move the money weekly; don’t leave it in checking, where it quietly becomes next week’s spending. Vague goals leak; named goals stick. And do a 10-minute pantry and freezer inventory before day one, then plan your first week of meals from what you already own — most households are sitting on a week of forgotten food. That’s your head start.
How Much Can You Realistically Save?
No honest guide will promise you a number. But here’s example math for estimating your own: if you normally spend about $250 a month eating out, $120 on impulse buys, $60 on coffee, and $80 on entertainment, pausing all four frees roughly $510 in theory. Your numbers will differ. Almost every finisher discovers one spending category that shocks them. For me it was food delivery — one discovery that saved me more in the following six months than the challenge month itself.
Can’t Face a Month? Start With a No-Spend Weekend
Shrink the challenge: zero discretionary spending from Friday evening to Monday morning. Cook from the pantry, find free local activities — parks, trails, free museum days, library events — and entertain the kids with what you own. Two days of success teaches you the mechanics (written rules, the 24-hour pause, saying no gracefully) and makes the full month feel achievable instead of terrifying.
After Day 30: Three Decisions
Finishing is great; day thirty-one matters more. Make three decisions: what comes back (some spending genuinely improves your life — bring it back by choice, not default); what stays cut (there’ll be at least one category you never missed — that’s where permanent savings live); and what one habit continues (the weekly transfer, the 24-hour rule, the meal plan — one habit kept forever beats a perfect month followed by relapse).
Want a follow-up challenge? Our 52-week money saving challenge guide picks up where this leaves off, and these money-saving tips for mums pair well with the no-spend mindset.
Frequently Asked Questions
What counts as essential spending in a no spend month?
Essentials keep your life running: housing, utilities, insurance, basic groceries, transport to work, medications, minimum debt payments, childcare, pet food. Everything else — eating out, clothes, entertainment, mid-month subscriptions, impulse buys — is discretionary. Draw the line before day one, in writing.
How do I start a no spend month?
Pick a start date (the first of the month is cleanest), write your allowed and not-allowed lists, decide every gray area in advance, name a destination for the saved money, tell at least one person, and do a pantry inventory plus one week of meal planning. An hour of prep determines the whole month.
How much can you save with a no spend month?
It depends entirely on your current discretionary spending — no honest universal number exists. To estimate: add up last month’s dining out, coffee, impulse buys, entertainment, and non-essential shopping. That’s your theoretical ceiling. Most finishers say the lasting value was the spending leak the month exposed, not the one-month total.
What’s the difference between a no spend month and a no buy month?
Mostly labeling. A no-spend month typically freezes all discretionary cash outflows (including services like haircuts or rideshares), while a no-buy month focuses more narrowly on physical purchases. For most people the practical difference is zero — pick the label you like.
Can I do a no spend month if I have kids?
Yes — just customize. Kid essentials (school supplies, outgrown shoes, medicine) are always allowed; kid wants follow the same freeze. Write a simple family agreement together, allow one small planned treat per person per week, and frame it as a team challenge. Many families say it becomes their best month for free together-time.
Conclusion
A no-spend month isn’t about suffering. It’s a thirty-day experiment in paying attention — and the written-rules method is what lets the experiment survive real life. Write the rules, decide the gray areas, name the destination, and give yourself a failure protocol instead of a guilt trip. Start this weekend with a no-spend Friday-to-Monday, or pick your start date right now while you’re motivated.
Your Savings Could Build Something Bigger: A Free Website Plan
This month you proved something valuable: you can redirect a few hundred dollars of “leak” money somewhere on purpose. Here’s a thought — what if some of that redirected money built an asset instead of just sitting in savings? A website costs less than one month of impulse purchases, and unlike money you simply didn’t spend, a website can keep working for you for years.
Two things worth knowing:
 🌐
Free Website
🌐 FREE Website — Turn Your Ideas Into Income
Want a handsome monthly income? Publish helpful articles consistently and let Google traffic grow into real earnings — steady work, never overnight magic. We never guarantee earnings.
Disclosure: This article contains an affiliate link. If you purchase hosting through it, we may earn a commission at no extra cost to you.
(2) If you’d like to earn a handsome amount every month, make a website and start writing helpful articles on it — Google traffic can turn into monthly income over time. It takes consistent articles and patience, not overnight magic, and there are no guaranteed earnings — but every big blog started with one article.
Buy hosting through our link, send us your receipt through the JobyRoz contact page, and we will guide your basic business website setup for FREE.
Disclosure: the Hostinger link above is a referral link — if you buy through it, we may earn a commission at no extra cost to you.
Want to see exactly how much your no-spend month could free up? Run your numbers through a savings calculator on EarnRove — and here’s a sneaky one: bottled water is one of the most common gray-area expenses people cut. A simple home filter pays for itself fast; see how at ClearOve.
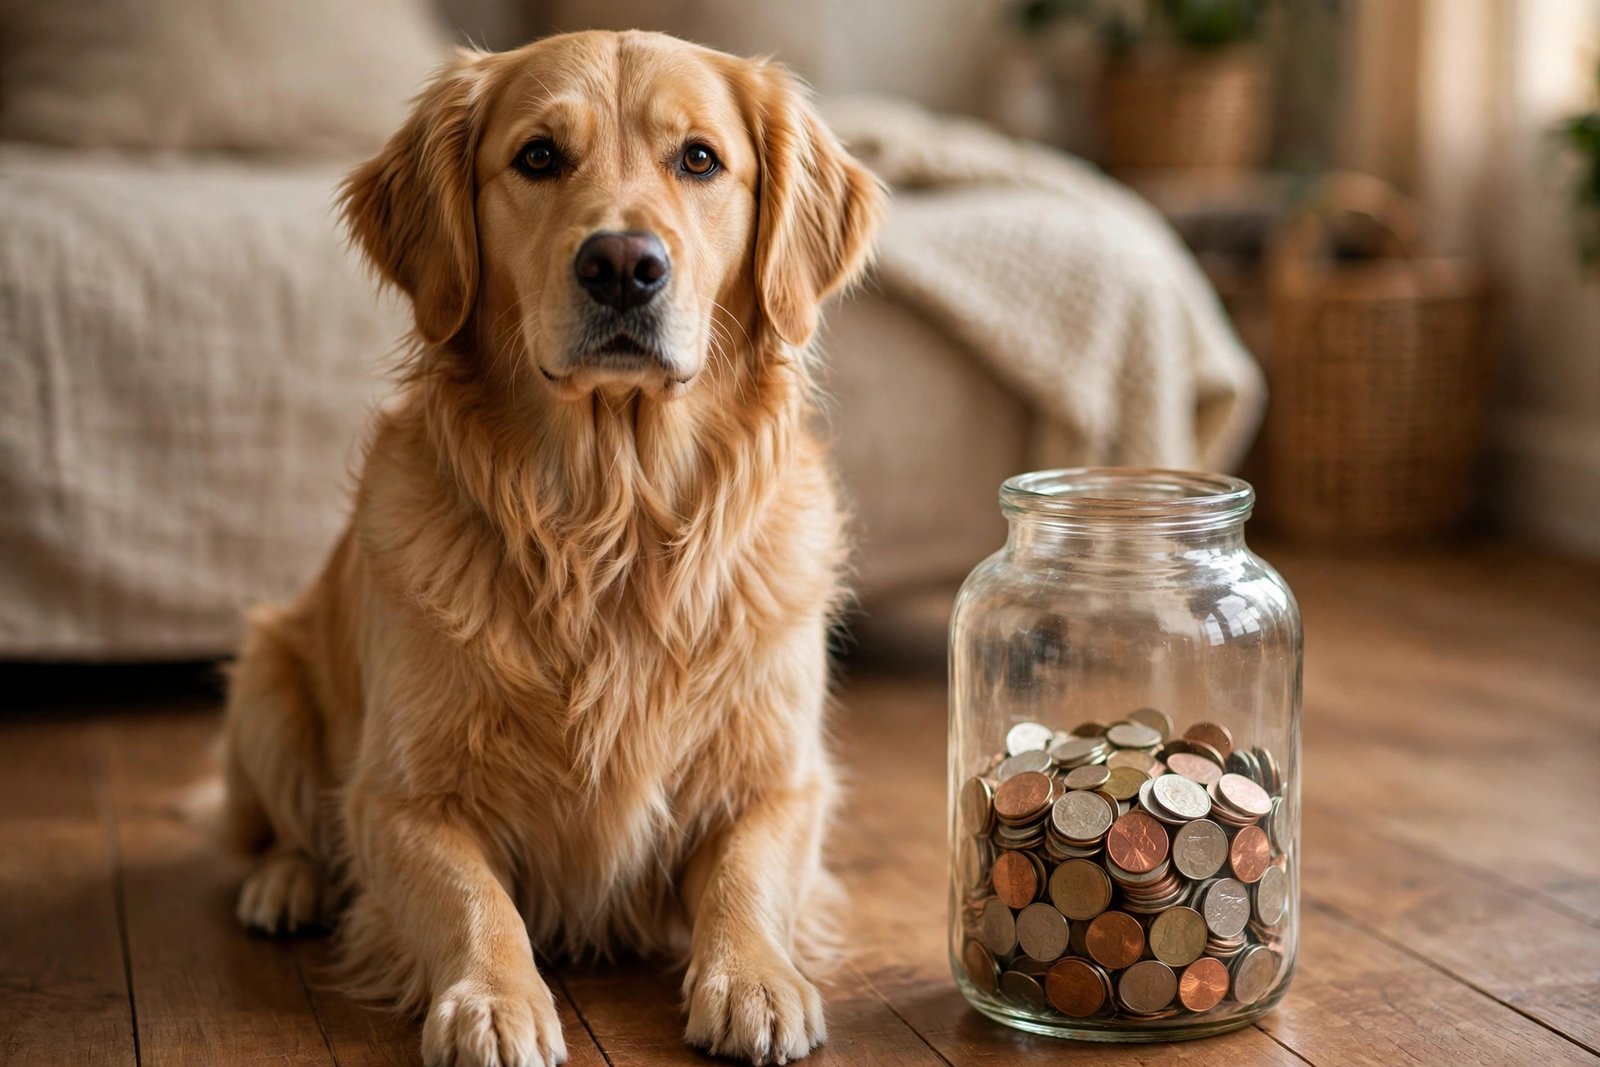
The Only Family Member Who Never Breaks the Rules
Here’s something funny: your dog already lives a no-spend month. He spends zero on impulse buys, uses exactly what he has, and has never once felt deprived about it. He’d guard that savings jar all month and never touch a cent. The one thing he can’t do is shop smart — so when he does need something, one wrong purchase is money straight down the drain. What does he actually need, and what’s just clever marketing?
 🐶
Free Pet Guides
🐶 Love Dogs Too?
🧮Money Tools
🧮 Earnrove — Free Money Calculators