Right now, there’s a decent chance your savings account holds less than a takeaway bill. You’re not unusual — roughly 1 in 10 UK adults have no savings at all, and another 21% have less than £1,000 tucked away, according to the FCA’s latest Financial Lives figures. This guide is the fix: a blunt, week-by-week plan to build your first £1,000 in 90 days.
Quick answer: To save £1,000 in 3 months in the UK, set aside £77 a week (about £333.33 a month, or £11.11 a day) for 90 days. The realistic mix: cut £15–20 a week from your biggest leaks (food, subscriptions, impulse spending) and earn £50–60 a week extra from one short-term boost — selling things you own or a few extra shifts. Automate the weekly transfer on payday so the money leaves before you can talk yourself out of it.
The Exact £ Maths: What £1,000 in 90 Days Really Takes
“Save £1,000 in 3 months” sounds enormous until you break it down:
| Time frame | Amount to set aside | How it adds up |
|---|---|---|
| Per day | £11.11 | £11.11 × 90 = £1,000 |
| Per week (13 weeks) | £76.92 — call it £77 | £76.92 × 13 = £1,000 |
| Per month | £333.33 | £333.33 × 3 = £1,000 |
| Per 9 days | £100 | 10 rounds of £100 = £1,000 |
Pick ONE unit and make it your number — £77 every Friday is concrete enough to hunt down. For context: Raisin UK found the average household burns about £12 a day on avoidable spending — nearly £4,600 a year. You don’t need to find £77 from nothing; you need to reclaim roughly £11 a day you won’t miss, or earn it.
Weeks 1–4: The Audit (Find Where Your £77 Is Hiding)
The first month isn’t about heroics. It’s about discovery.
Week 1 — the leak hunt. Write down every pound you spend for seven days — phone notes or the back of a receipt envelope, nothing fancy. You’ll spot 2–3 leaks immediately: the £2.50 daily coffee, the £1 water bottle, the subscription you forgot existed. Skipping that coffee and water alone is worth £245 over ten weeks — nearly a quarter of your target from two habits.
Week 2 — the subscription cull. Go through your bank statement line by line. Most people find £20–£40 a month of pure waste: streaming services unopened for weeks, forgotten app renewals, insurance extras. Cancel, don’t downgrade. You can re-add in month four.
Week 3 — the food reset. Food is the biggest controllable bill in most UK households — the average household spends over £5,200 a year on it. Run the five-swap trick: switch five branded items to own-brand, plan one week of meals, and cook double twice a week for leftovers. Our UK groceries guide (25 grocery tactics that save £100+/month) found these swaps can be worth £483 a year. Week-3 target: £20 back.
Week 4 — open the separate pot. Set up a separate savings pot — Monzo, Starling, and most UK banks do it in minutes. Name it something annoying to touch, like “DO NOT SPEND — £1,000 PLAN”, and set a £77 standing order for payday. From now on, saving happens automatically and spending gets what’s left. It’s the same pay-yourself-first mechanic behind the sinking funds system, pointed at one target.
Target balance after week 4: ~£250.
Weeks 5–8: The Boost (Add £50–£60 a Week From Outside Your Income)
Cutting can only take you so far. This phase is about earning.
The sell-off sprint. Fill a carrier bag with things you haven’t touched in a year and list them on Vinted or Facebook Marketplace in one evening. Most declutter rounds raise £100–£300 within a fortnight.
The short-term extra shift. Overtime, a Saturday shift, agency work — whatever your job and schedule allow, for 90 days only. You’re not signing up for a second career; you’re renting out your evenings for three months. An extra £60 a week for eight weeks is £480.
The bill-shake. Call your broadband, mobile, and insurance providers and ask for a better deal — or switch. Our UK energy-bills guide shows there’s still real money here: the October 2026 price cap, the £150 Warm Home Discount for eligible households, and VAT off domestic electricity until March 2027. Even £30–£40 a month is a permanent raise.
Every extra pound goes into the pot the day it arrives — before it becomes “spending money”. Target balance after week 8: ~£650.
Weeks 9–12: The Lock-In (Don’t Blow It in Week 10)
Most savings challenges die in week 10, when fatigue sets in and something tempting appears. Guard against it with rules, not willpower: write a simple contract — the pot is not for convenience, only true emergencies qualify, anything borrowed gets replaced the next week. It’s the same written-rules approach that keeps people past day 10 in our no-spend month guide.
Run one strict no-spend week in the final stretch — no eating out, no shopping — and recapture £50–£80 almost effortlessly, since the hard habits are already built. Watch for “almost-emergencies”: sales, the new phone your contract is nagging you about, a mate’s expensive birthday dinner. None of these are emergencies. A £100 setback moves the finish line a few days; it doesn’t cancel the plan.
Week 12 — count the pot. At £1,000, move it to a proper easy-access account and rename it “EMERGENCY FUND — HANDS OFF”. At £800–£900, extend by two weeks. At £600, that’s still likely the most you’ve ever saved at once — and one more cycle finishes the job.
UK-Specific Levers Most Guides Never Mention
Generic “save £1,000 in 90 days” guides are almost all American. Here’s what applies to a UK reader in 2026:
Help to Save is now permanent. In September 2026 the government confirmed the scheme — a 50p bonus for every £1 saved, up to £50 a month — is permanent rather than closing in April 2027. For working Universal Credit claimants it’s a 50% return — the best guaranteed savings rate in the UK. Bonuses land at year 2 and year 4, so it won’t fund your 90 days — but open one during the challenge and your next savings phase is on autopilot.
£150 Warm Home Discount + VAT off electricity. Eligible households get £150 off their electricity bill this winter, and VAT is off domestic electricity until March 2027. Money that stays in your pocket routes straight to the pot.
£800 a year in food waste. WRAP and Tesco Bank put UK food waste at roughly £800 a household per year. Meal planning and proper leftovers are worth as much as a part-time side hustle for many families.
Cash stuffing works for sprints. If digital pots feel too easy to raid, the physical envelope method keeps money visible. Our cash stuffing UK guide starts with just £50 — perfect for the weekly £77 in physical form.
7 Mistakes That Kill 90-Day Savings Plans
- Starting at £77 when £30 is honest. If £77 a week is genuinely impossible, save £30 and extend the timeline. A doable plan beats a heroic one you quit in week 2.
- Keeping the money in your spending account. If the pot sits where you spend, it’s not savings — it’s delayed spending. Separate account, no debit card.
- Cutting AND earning in week 1. That’s the audit phase. Early burnout is the number-one plan killer — one lever per phase.
- Calling sales “emergencies”. Define emergencies while you’re calm: job loss, car MOT failure, boiler breakdown, urgent medical or dental. A 30%-off code isn’t on the list.
- Skipping the weekly check-in. Sunday night, 10 minutes: balance, what leaked, next week’s plan. Trackers hit targets; “it feels fine” doesn’t.
- Ignoring the budget underneath. If every month structurally ends at zero, the £1,000 evaporates after day 90. Run zero-based budgeting alongside so each pound keeps a job afterwards.
- Confusing this with escaping debt. If you’re on the overdraft treadmill, read our paycheck-to-paycheck 90-day escape plan first — that one targets the debt cycle (£100/£300/£500 milestones). This plan builds your first buffer. The order matters.
What to Do With the £1,000 After Day 90
Three rules. One: don’t spend it — it’s not a holiday fund (the 52-week challenge has those covered). Two: keep it easy-access for when the boiler dies. Three: give it a next job — £50 a week for three more months gets you to £1,600, and that’s when real peace of mind starts.
This is a practical savings plan, not regulated financial advice. If your finances feel unmanageable, the free charity StepChange can help you talk through options without judgment.
FAQ
Is it realistic to save £1,000 in 3 months on a low income?
Harder, not impossible — lean on earning instead of cutting: one declutter sell-off (£100–£300), extra shifts, or agency work does most of the lifting. Fallback: run it at £30–£40 a week and aim for £500. Still a buffer you didn’t have.
Should I save the £1,000 or pay off debt first?
Save a small buffer first (£500–£1,000), then attack expensive debt. Without any buffer, the next surprise expense lands back on a credit card and undoes your debt progress.
Where should I keep the money during the 90 days?
A separate savings pot or account you don’t see in daily banking — easy-access, no debit card, no overdraft attached. Avoid cash at home: too easy to spend, impossible to track.
Can I use Help to Save for this 90-day challenge?
Not directly — its bonuses pay out at year 2 and year 4. But working Universal Credit claimants should open one during the challenge: the 50% bonus on up to £50 a month is the UK’s best guaranteed savings return, and it gives your money a purpose after day 90.
What if I fail halfway through?
Then you keep whatever you’ve saved — which beats where you started. Extend the timeline, fix what went wrong that week, and continue. The only real failure is dropping the habit because the plan wasn’t perfect.
The Finish Line Is £1,000 of Proof
What £1,000 in 90 days really buys: proof — proof you can set a financial goal and hit it, and that you can delay gratification for three months. That confidence carries into the next target.
Start tonight. Open the separate pot, schedule the first £77 transfer for your next payday, and write down what you spend this week. Ninety days from now, the boiler can break or the car can fail its MOT — and for the first time, it won’t be a crisis. That’s what the first £1,000 really is: breathing room.
For more ideas in the Personal Finance section, browse our latest money-saving guides.
Build a Free Website That Earns While Your Savings Sleep
Once that £1,000 buffer is sorted, here’s the next move: it protects you, but it doesn’t grow. These days every serious small business needs a website — and setting one up has never been simpler. Grab hosting through our link below, tell the built-in AI what your business is about, and it builds the site for you. No coding, no designer, no fuss.
 🌐
Free Website
🌐 FREE Website — Turn Your Ideas Into Income
Want a handsome monthly income? Publish helpful articles consistently and let Google traffic grow into real earnings — steady work, never overnight magic. We never guarantee earnings.
Disclosure: This article contains an affiliate link. If you purchase hosting through it, we may earn a commission at no extra cost to you.
And I’ll be straight with you: a website plus consistent helpful articles can turn into a monthly income stream through Google traffic. It takes daily writing, not overnight magic, and nobody can promise you earnings — but a £1,000 buffer plus a small site bringing in pocket money each month is a far calmer place to live than a £1,000 buffer alone.
If you do grab hosting through our link, send us your receipt through the JobyRoz contact page and we’ll guide your basic business website setup for FREE — theme choice, first pages, the lot.
Disclosure: the link above is an affiliate link. If you buy through it, JobyRoz may earn a commission at no extra cost to you. We only recommend services we’d use ourselves.
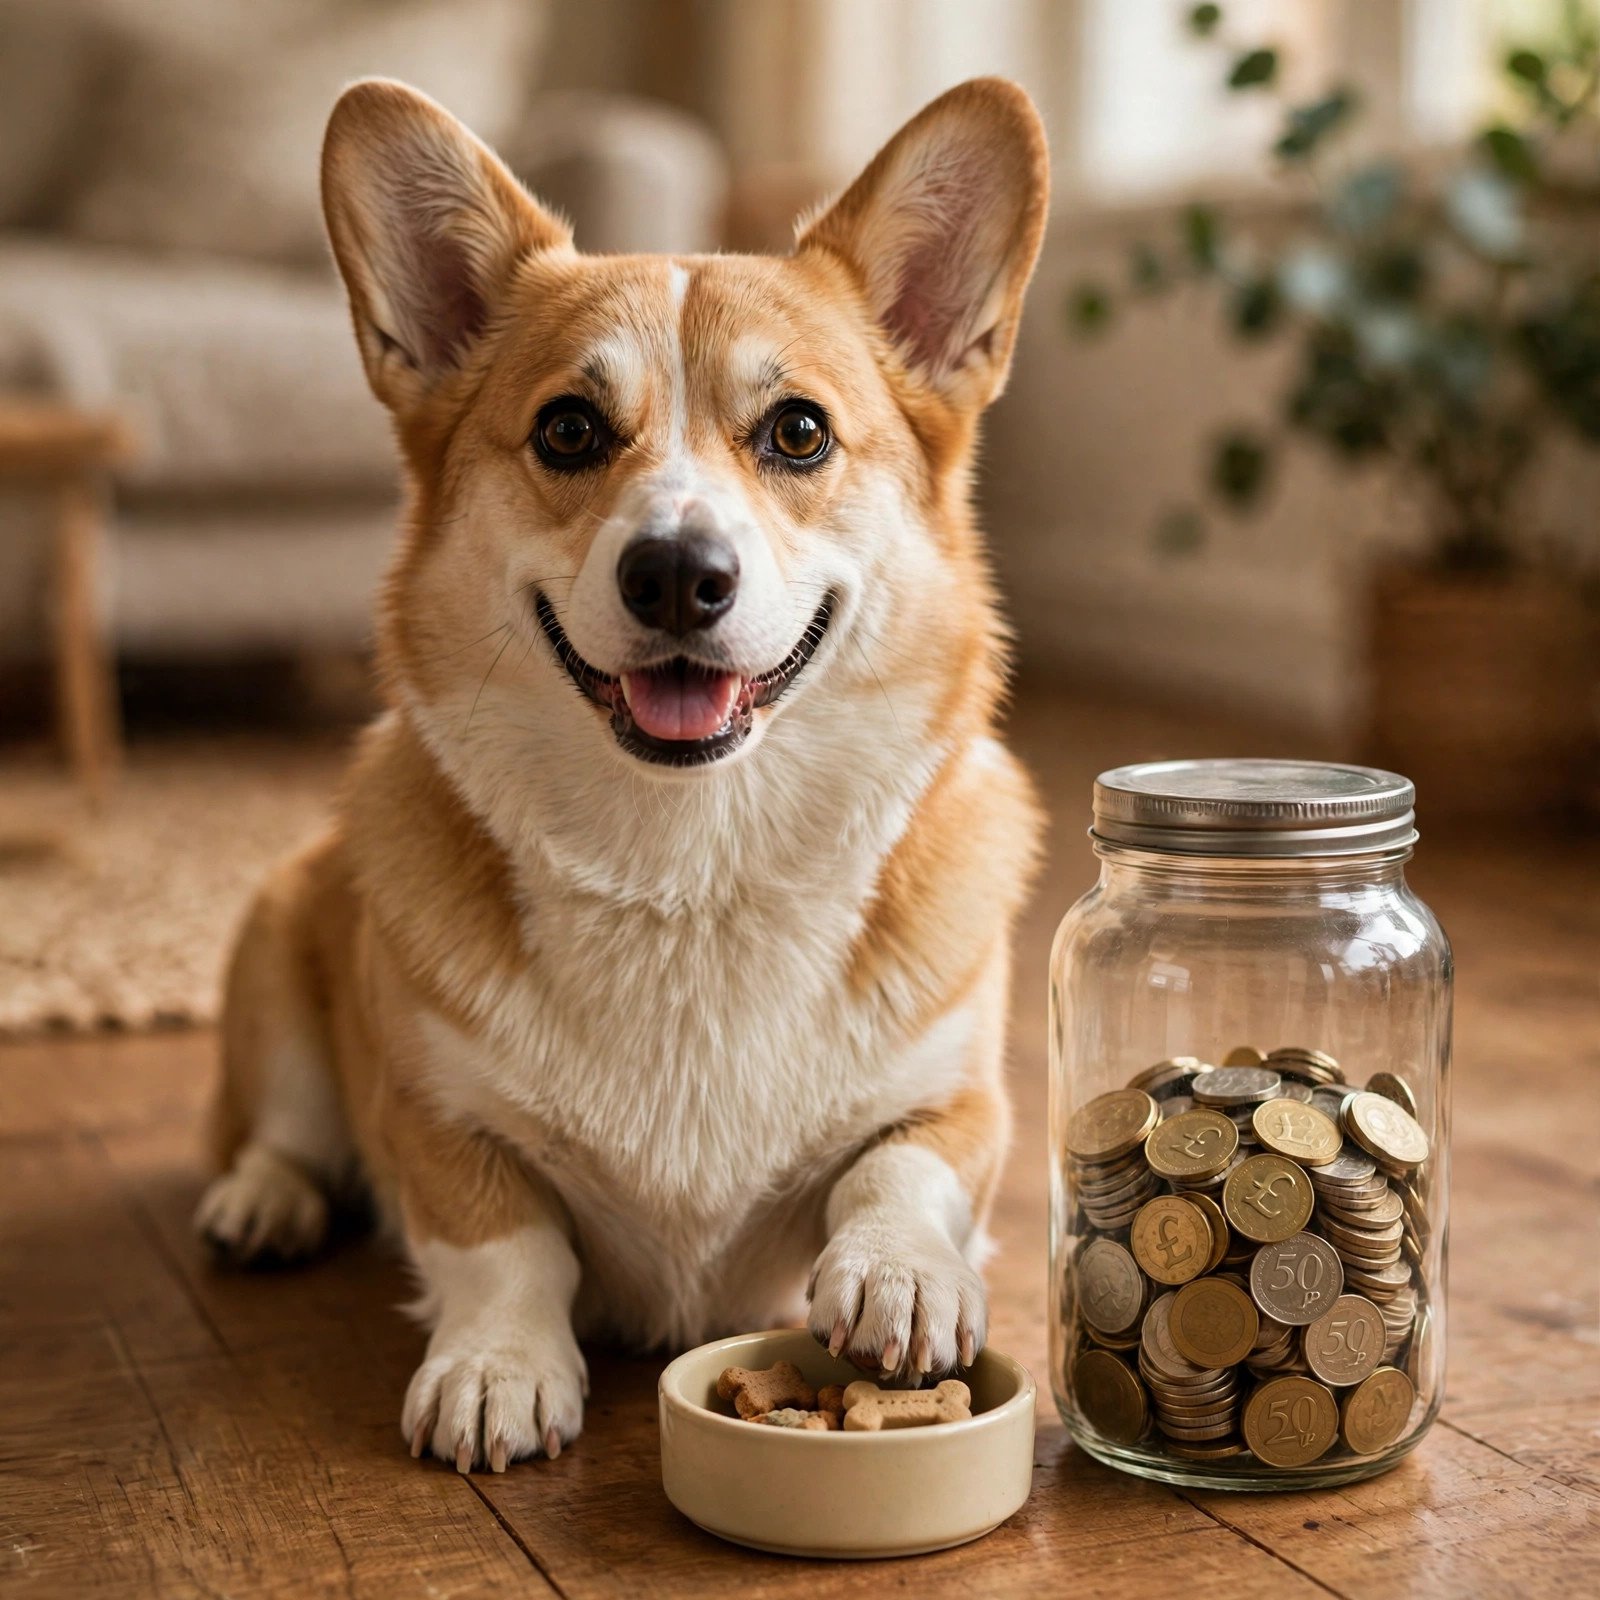
The Financial Planner Who Charges in Treats
Our favourite money manager works for biscuits, not bonuses. He keeps one paw on the treat bowl and the other on the savings jar — and somehow the jar always fills up. If a corgi can budget for treats without a single spreadsheet, your £77-a-week plan is in safe paws.
 🐶
Free Pet Guides
Ready to hire your own four-legged finance team?
More ways to grow your money: run the numbers with the free money tools and calculators at Earnrove, and keep your household costs clean with the clean-water guides at Clearove.
🧮Money Tools
🧮 Earnrove — Free Money Calculators